This page gives you Chapter 3, Money and Credit, from the NCERT Class 10 Economics textbook Understanding Economic Development — the chapter opens on printed page 37 of the official edition published on ncert.nic.in.
You can download the official Money and Credit Class 10 chapter PDF free of charge straight from the NCERT website; below is a section-by-section map of everything inside the file, with the printed page numbers so you can follow along in the book.
Download the official Money and Credit Class 10 chapter PDF
Money and Credit is Chapter 3 of the NCERT Class 10 Social Science book Understanding Economic Development, the volume that carries the Economics part of the Class 10 Social Science syllabus.
The official Money and Credit Class 10 chapter PDF is hosted by NCERT itself and matches the printed textbook page for page, so the text on your screen is exactly what appears in the book.
Inside the file: money as a medium of exchange, modern forms of money such as currency and bank deposits, cheque payments, and how banks turn deposits into loans.
Then the chapter moves to two different credit situations, the terms of credit, the Sonpur village survey, formal and informal credit, self-help groups and the Grameen Bank, and it closes with a summing up and the end exercises.
Chapter at a glance: what is inside Money and Credit
The table below maps the chapter’s main topic blocks to the printed textbook pages, so you can jump straight to any idea without reading the whole chapter.
| Topic block in Money and Credit | Printed pages |
|---|---|
| Money as a medium of exchange; double coincidence of wants | p. 39 |
| Modern forms of money: currency, deposits with banks, cheques | pp. 40-41 |
| Loan activities of banks: deposits become loans | p. 42 |
| Two different credit situations: Salim and Swapna | p. 43 |
| Terms of credit: interest, collateral, documents, repayment | pp. 44-45 |
| Credit in a village: Sonpur’s farmers and landless labourers | pp. 46-47 |
| Formal and informal credit: who gets what | pp. 48-49 |
| Self Help Groups and Grameen Bank | pp. 50-52 |
| Summing up and the chapter’s exercises | pp. 52-53 |
What Money and Credit Class 10 covers, section by section
Before the detail, here is the shape of the whole chapter in a few sentences. Money and Credit runs from NCERT page 37 to page 52 of Understanding Economic Development.
The first half of the chapter is about money. It starts from the old problem of barter, then shows how modern money works as currency plus demand deposits, and how cheques and banks fit in (NCERT, pp. 37-41).
The second half is about credit — loans. It compares credit that helps a borrower with credit that creates a debt trap, explains the terms of every loan, and contrasts cheap formal credit with costly informal credit (NCERT, pp. 42-49).
The chapter also notes how Indian payment habits have changed since the November 2016 demonetisation, with more transactions moving through bank transfers, cards, point-of-sale machines and UPI rather than cash (NCERT, p. 37).
Money as a medium of exchange: the barter problem
This section answers the chapter’s first real question: why does money exist, and why is buying with money easier than swapping goods?
Before money, exchange meant barter — goods swapped directly for goods. Barter works only when each side wants exactly what the other side is offering. This matching condition is called double coincidence of wants (NCERT, p. 39).
The chapter’s shoe manufacturer wants to sell shoes and buy wheat. Without money he must find a wheat-growing farmer who also wants shoes — his wish and the farmer’s wish must coincide.
With money the match is unnecessary. He sells shoes to any buyer, receives money, and buys wheat from any seller. Because money sits in the middle of the exchange, it is called a medium of exchange (NCERT, p. 39).
So the answer to “How does the use of money make it easier to exchange things?” is: money removes the need for double coincidence of wants by providing an intermediate step that everyone accepts.
The cartoon on page 39 (explained in the figure walkthrough below) pictures exactly this mismatch of wants.
Modern forms of money: currency, deposits and cheques
This section explains the forms of money you use today — currency, bank deposits and the cheques that move deposits around — and why people accept them.
Money has a long history. In early times Indians used grains and cattle as money; later came metallic coins of gold, silver and copper, a phase that continued well into the last century (NCERT, p. 40).
Modern currency — the notes and coins in your pocket — is different. It has no use of its own: it is neither precious metal nor everyday goods. People accept it because the government authorises it.
In India, the Reserve Bank of India issues currency on behalf of the central government, and no one else may issue it. By law, rupees cannot be refused in settling transactions (NCERT, p. 40).
The second form of money is the demand deposit — money kept in a bank account, withdrawable on demand and earning interest. The words “on demand” matter: the bank must return the money whenever you ask (NCERT, pp. 40-41).
A cheque is a paper instruction to the bank to pay a specific amount from the payer’s account to the person named on the cheque (NCERT, p. 41).
Here is the step-by-step path of a cheque payment, with original names:
- Farida runs a tailoring shop in Jaipur. She owes Meera Fabrics Rs 12,000 for cloth.
- Farida writes a cheque for Rs 12,000, names Meera Fabrics as the payee, and hands it over — no cash leaves her shop.
- Meera deposits the cheque into her own bank account.
- Over the next couple of days the two banks transfer Rs 12,000 from Farida’s account to Meera’s account.
- The transaction is complete: Farida’s balance is down by Rs 12,000 and Meera’s is up by the same amount.
Notice that no cash moves anywhere. That is why the chapter’s check-question has answer (ii): after the payment, the payer’s balance falls and the payee’s rises (NCERT, p. 41).
If Salim wants to withdraw Rs 20,000 in cash for himself, he would write a cheque in his own name — payable to “self” — and present it at the bank, since the person named on a cheque is the one entitled to the amount.
Because demand deposits can settle payments directly through cheques, they share the essential features of money and, with currency, make up modern money (NCERT, p. 41).
How banks work: deposits become loans
This section shows what a bank does with the deposits it collects — and why that turns the bank into a bridge between savers and borrowers.
Banks do not keep all the money they receive. In India these days they hold only a small proportion of deposits as cash — roughly 5 per cent — set aside for the depositors who come to withdraw on any given day (NCERT, p. 42).
The major portion of deposits is lent out as loans. In this way banks mediate between people with surplus funds, the depositors, and people who need funds, the borrowers.
Banks charge a higher interest rate on loans than they offer on deposits; the difference is their main source of income (NCERT, p. 42).
The chapter’s follow-up question: what if all depositors asked for their money at the same time? The bank could not pay everyone, because most of the deposited money has already been lent out (NCERT, p. 42).
Credit that helps and credit that harms: Salim and Swapna
Two stories on the same page — one where credit lifts a borrower, one where it ruins her — carry the central lesson of the chapter.
Credit (or loan) is an agreement in which the lender supplies money, goods or services now, in return for a promise of future payment (NCERT, p. 43).
The table below fills in the two cases exactly as the chapter’s exercise asks you to.
| Question the chapter asks | Salim (shoe manufacturer) | Swapna (small farmer) |
|---|---|---|
| Why did they need credit? | Working capital for a festival order: raw materials and extra workers. | The expenses of growing groundnut on her three acres. |
| What was the risk? | The order might not be completed or paid on time. | Pests could destroy the crop before harvest. |
| What was the outcome? | The order was delivered, he made a profit and repaid his loans. | The crop failed, the debt grew, and she had to sell part of her land. |
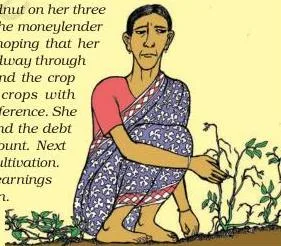
Swapna’s situation is a debt trap: the harvest fails, the loan cannot be repaid, the debt grows over the year, and she must sell part of her land to clear it (NCERT, p. 43).
The lesson of the two stories: whether credit helps depends on the risk in the situation and on whether some support exists in case of loss (NCERT, pp. 43-44).
Terms of credit: interest, collateral, documents and repayment
Every loan comes with conditions. Together these conditions are the terms of credit, and they decide whether a loan is cheap or costly.
The terms of credit are four things: interest rate, collateral, documentation requirement and mode of repayment (NCERT, p. 45).
Collateral is an asset the borrower owns — land, a building, a vehicle, livestock or bank deposits — used as a guarantee to the lender. If the borrower fails to repay, the lender has the right to sell it (NCERT, p. 44).
The book’s example is Megha’s housing loan of Rs 5 lakhs at 12 per cent per annum, repaid in monthly instalments over 10 years; the bank kept the house papers as collateral until the loan was fully repaid (NCERT, p. 45).
Because collateral matters so much, poor borrowers who own little find it harder to borrow. Lenders ask for collateral to protect their money if the loan is not repaid.
A borrower’s ideal terms would be a low interest rate, easy repayment conditions, and less collateral and documentation — exactly the answers the chapter’s blanks ask for (NCERT, p. 45).
Credit in a village: Shyamal, Arun and Rama
The chapter then visits Sonpur, a small irrigated village, to show how the terms of credit differ for a small farmer, a medium farmer and a landless labourer.
The table compares the three borrowers interviewed by the students Rohit and Ranjan on 15 November 2019 (NCERT, pp. 46-47).
| Borrower | Interest rate and terms | What it means for the borrower |
|---|---|---|
| Shyamal, small farmer (1.5 acres) | Earlier: moneylender at 5% per month (60% per year). Now: agricultural trader at 3% per month (36% per year). | Must buy inputs from the trader and promise to sell him the crop, so the trader profits twice. |
| Arun, medium farmer (7 acres) | Bank loan at 8.5% per annum, repayable within three years. | Can store potatoes and take a fresh loan against the cold storage receipt; sells later at a better price. |
| Rama, landless labourer | Employer (a medium landowner) at 5% per month; repaid by working. | Must take fresh loans before old ones are repaid; owes Rs 5,000; the landless have no other source. |
Arun earns more from cultivation than Shyamal for two linked reasons: his bank credit is far cheaper, and after harvest he stores his potatoes in a cold storage instead of selling at the low post-harvest price (NCERT, p. 46).
Only a few villagers get bank loans, because banks demand collateral that most villagers cannot provide (NCERT, p. 47).
Cooperatives are the other major source of cheap rural credit. Krishak Cooperative, near Sonpur, has 2,300 farmer members; it accepts members’ deposits, uses them as collateral to borrow a large sum from a bank, and lends the funds back to members (NCERT, p. 47).
The production side of these farming loans is covered in the Class 10 Geography notes on Agriculture.
Formal and informal credit: who gets what
This section sorts every lender in India into two baskets — formal and informal — and shows which basket the poor are actually borrowing from.
Formal sector credit comes from banks and cooperatives; informal sector credit comes from moneylenders, traders, employers, relatives and friends (NCERT, p. 48).
The chapter’s credit data come from the All India Debt and Investment Survey 2019, the NSSO’s 77th Round (NCERT, p. 37).
The Reserve Bank of India supervises the formal sources. It ensures banks keep the minimum cash balance, checks that they lend to small cultivators and small borrowers and not only to profit-making businesses, and banks must regularly report how much they lend and at what rate (NCERT, p. 48).
Informal lenders have no supervisor. They charge whatever interest they choose and are free to use unfair means to recover money, so the cost of an informal loan is much higher for the borrower (NCERT, p. 48).
The chapter’s data make the pattern stark: 54 per cent of the loans taken by poor urban households come from informal sources, against only 17 per cent for rich urban households, whose loans are 83 per cent formal. A similar pattern holds in rural areas (NCERT, p. 49).
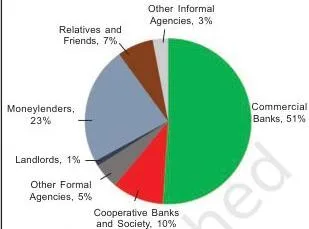
Across rural India, the formal sector still meets only about half of total credit needs; the rest comes from informal sources (NCERT, p. 49).
The chapter draws two conclusions: banks and cooperatives must lend more, especially in rural areas, and formal credit must be distributed more equally so the poor share in cheaper loans (NCERT, p. 49).
For current banking statistics, the chapter’s source note points to the Reserve Bank of India website (NCERT, p. 37).
The real cost of costly credit: a worked comparison
A rate of 2 per cent per month sounds small until you multiply it by twelve. This worked example puts the Sonpur rates on one amount so you can see the gap.
Priya needs Rs 10,000 for one year. Her local bank charges 8.5 per cent per annum — the rate Arun pays in Sonpur. A moneylender charges 2 per cent per month.
Step 1: Bank loan at 8.5 per cent per annum for one year:
\[ \text{Interest} = \frac{8.5}{100} \times 10{,}000 = \text{Rs } 850 \]
Step 2: Moneylender at 2 per cent per month, which is 24 per cent for the year:
\[ \frac{2}{100} \times 10{,}000 = \text{Rs } 200 \text{ per month} \]
\[ 200 \times 12 = \text{Rs } 2{,}400 \text{ for the year} \]
Conclusion: the informal loan costs Rs 2,400 against Rs 850 — about three times as much for the same amount and the same period, leaving Priya far less income for herself.
This is an illustration built from the range of rates found in Sonpur (NCERT, p. 46), not a textbook example. The conversions work the same way: 3 per cent per month equals 36 per cent per year, and 5 per cent per month equals 60 per cent per year, the rate Shyamal once paid to the moneylender.
The chapter adds a warning: when the amount to be repaid can exceed the borrower’s income, debt grows — as with Rama — and the high cost of borrowing can also stop people from starting enterprises (NCERT, p. 48).
Self Help Groups and Grameen Bank: credit for the poor
The poor face a chicken-and-egg problem: no collateral, so no bank loan; no bank loan, so they stay poor. Self Help Groups and Grameen Bank are two organised ways out of this loop.
A Self Help Group (SHG) is a small savings circle of 15-20 members, usually women from one neighbourhood, who meet regularly and save from Rs 25 to Rs 100 or more per member (NCERT, p. 50).
Members can take small loans from the group’s own pool at interest lower than the moneylender’s. After a year or two of regular savings, the group becomes eligible for a loan from a bank (NCERT, p. 50).
The bank sanctions the loan in the group’s name. The members decide each loan’s purpose, amount, interest and repayment schedule, and the group as a whole is responsible for repayment — this collective responsibility is why banks lend without collateral (NCERT, pp. 50-51).
The wider gains: women become financially self-reliant, and regular meetings give a platform to discuss health, nutrition and domestic violence (NCERT, p. 51).
Grameen Bank of Bangladesh, started in the 1970s, had over 9 million members in about 81,600 villages by 2018, almost all of them poor women. Its founder Muhammad Yunus received the 2006 Nobel Peace Prize (NCERT, p. 52).
Yunus on the idea: “If credit can be made available to the poor people on terms and conditions that are appropriate and reasonable, these millions of small people with their millions of small pursuits can add up to create the biggest development wonder.”
Figure walkthrough: reading the NCERT diagrams in this chapter

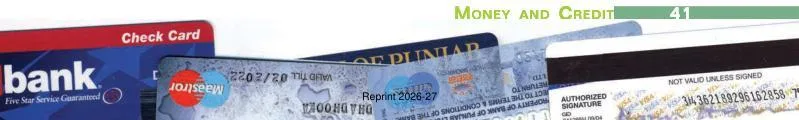
This section is a reading tour of the chapter’s key diagrams — the cartoons, coins, photos and the graph that NCERT uses to make the ideas visual. Each figure below is the one on that printed page.
The barter cartoon (p. 39)
The cartoon shows the double coincidence problem in one frame: a farmer offers shoes for wheat, but the other farmer wants clothes, and a third wants shoes without having wheat. Nobody trades, because the two sides’ wants never coincide — exactly the problem money solves.
Money through history (p. 40)
These two images sit side by side in the chapter to show that money is old. The punch-marked coins may be about 2,500 years old; the gold mohar belongs to Akbar’s reign. Both are metallic money — the long phase between grain-and-cattle money and today’s paper currency.
The role of banks (p. 41)
The chapter places this picture exactly where it explains cheque payments, with a caption asking you to remember the role banks play here. The point: without banks there would be no demand deposits and no cheques against them; modern money is tied to the banking system.
Two credit outcomes (p. 43)
The first picture shows credit working. By the end of the month, Salim has delivered the festival order, made a good profit and repaid the money he borrowed.
The second picture shows credit failing. Swapna’s groundnut crop is hit by pests midway through the season; the harvest fails, the moneylender’s loan becomes a growing debt, and she ends up selling part of her land.
Terms of credit and the Sonpur survey (pp. 45-46)
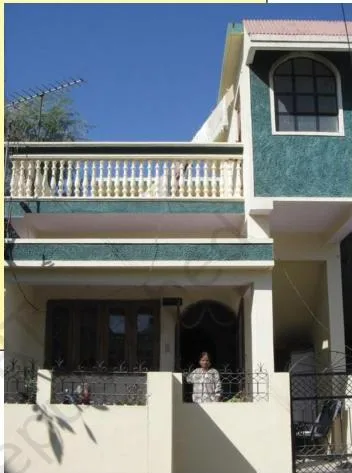
The house-and-loan image on page 45 ties the terms of credit to Megha’s housing loan — interest rate, collateral, documentation and mode of repayment.
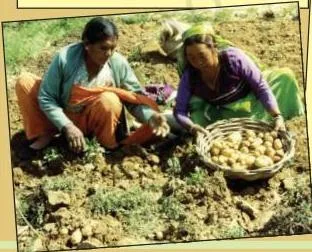
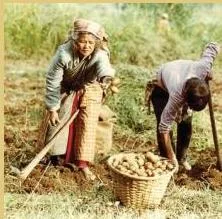
The two photos open the Sonpur case study: Rohit and Ranjan set out to record who lends in their village, and they find Rama working in a neighbouring field, dependent on her employer for every loan.
Cooperatives and Graph 1 (pp. 47-48)
The Krishak Cooperative image shows the cooperative roundabout: farmers pool deposits, the cooperative pledges them as collateral for a bank loan, and the funds are lent back to members for implements, cultivation and other needs.
Graph 1 on page 48 shows the sources of credit in rural India in 2019. The chapter asks you to read whether more credit comes from the formal or the informal sector; the text answers on page 49: the formal sector meets only about half of rural credit needs, the rest coming from informal lenders.
Key definitions from Money and Credit, in your own words
These are the chapter’s exam words in plain language, each written so you can use it directly in an answer.
| Term | Plain meaning | NCERT page |
|---|---|---|
| Medium of exchange | Something that sits between the goods you sell and the goods you buy, and is accepted by everyone in payment. | p. 39 |
| Double coincidence of wants | The barter condition where what one person wants to sell is exactly what another wants to buy. | p. 39 |
| Barter | Direct exchange of goods and services without using money. | p. 39 |
| Currency | The notes and coins that a government authorises as payment. | p. 40 |
| Demand deposits | Money kept in a bank account that can be withdrawn on demand and earns interest. | pp. 40-41 |
| Cheque | A paper instruction to the bank to pay a specific amount from one account to the person named. | p. 41 |
| Collateral | An asset the borrower owns, pledged as a guarantee that the loan will be repaid. | p. 44 |
| Terms of credit | Interest rate plus collateral plus documentation requirement plus mode of repayment. | p. 45 |
| Formal sector credit | Loans from banks and cooperatives, supervised by the Reserve Bank of India. | p. 48 |
| Informal sector credit | Loans from moneylenders, traders, employers, relatives and friends, with no supervisor. | p. 48 |
| Debt trap | A situation where a borrower cannot repay and the debt keeps growing, forcing fresh loans or the sale of assets. | p. 43 |
| Self Help Group | A member-run savings group of 15-20 people that lends small sums to its members and later borrows from a bank in the group’s name. | p. 50 |
Common mistakes in Money and Credit and how to avoid them
These are the errors students make most often in this chapter. Read them once to recognise them and once to avoid them in your own answer.
| Mistake | Correct rule | How to check your answer |
|---|---|---|
| “A cheque is money.” | A cheque is an instruction to the bank; the money is the demand deposit behind it. | Ask what moves when the cheque clears — the deposit moves, not the cheque. |
| “Banks keep all deposits as cash.” | Banks keep a small proportion (about 5 per cent these days) and lend the rest. | Test with the chapter’s question: if all depositors withdrew at once, the bank could not pay everyone. |
| “Credit always helps the borrower.” | Credit helps or harms depending on risk and on support in case of loss. | Compare Salim with Swapna: did the borrower’s earnings cover the repayment? |
| “Collateral is the amount borrowed.” | Collateral is the borrower’s own asset pledged as a guarantee. | Check whose asset it is and who can sell it on default. |
| “The RBI supervises all lenders.” | The RBI supervises banks and cooperatives; informal lenders have no supervisor. | Ask which basket the lender belongs to before saying who supervises it. |
| “An SHG is a bank.” | An SHG is a member-run savings group; the bank lends to the group, not to each member. | Ask who decides the loan purpose and repayment schedule — the members. |
Three small traps from the chapter’s own exercises are worth pinning down:
- After a cheque payment, the payer’s balance falls and the payee’s rises — never the other way round.
- Over the years, Rama’s debt will rise, because she takes a fresh loan before the earlier one is repaid.
- Arun is one of the few villagers to get a bank loan because banks demand collateral that most others cannot provide.
How to answer Money and Credit questions well
Every end question in this chapter carries a command word. Match your answer to that command and you will answer exactly what is asked.
- Explain — give the definition first, then show how the idea works, with a short example.
- Give an example of your own — never copy the book’s; change the goods, the amount or the people.
- Compare — set out both sides and say which is better or worse, and why.
- Analyse or Discuss — weigh both arguments and close with a clear conclusion.
The table maps the 13 end exercises of the chapter to the concept each tests and what a full answer needs.
| Question | Concept it tests | What a full answer must include |
|---|---|---|
| 1 | Debt trap | The chain: high risk → income fails → loan unpaid → debt grows → asset sold. |
| 2 | Double coincidence of wants | Definition, an example of your own, and money as the intermediate step. |
| 3 | Banks as mediators | Depositors with surplus, borrowers with need, and banks lending deposits in between. |
| 4 | Currency and the RBI | Read the note: RBI issues currency on behalf of the central government; rupees cannot be refused. |
| 5 | Expanding formal credit | The two conclusions: formal lending must grow and must reach the poor. |
| 6 | Self Help Groups | 15-20 members, regular savings, group decisions, bank loan in the group’s name. |
| 7 | Why banks refuse some borrowers | No collateral, no proper documents, and the risk of non-repayment. |
| 8 | RBI supervision of banks | Minimum cash balance, lending to small borrowers, periodic reports to the RBI. |
| 9 | Credit for development | Both faces: credit finances farming, business and industry; costly credit blocks them. |
| 10 | Bank vs moneylender | Compare interest, collateral, documents and repayment; the borrower’s circumstances decide. |
| 11 | Small farmers and cheap credit | Four parts: why banks refuse, other sources, one unfavourable example, and SHG/cooperative ways out. |
| 12 | Definitions | The blanks: poor; high; RBI; deposits; collateral. |
| 13 | Classification | (i) Members; (ii) Employers — employers are informal lenders. |
Finally, check the current official syllabus before the exam — textbook contents and the examinable syllabus are not always identical.
Need more around this book? the Class 10 notes hub collects chapters from every subject, and the main CBSE notes index covers other classes as well.
Money and Credit in four minutes: revision summary
This is the chapter’s own summing up (NCERT, p. 52), tightened into six lines for quick revision.
- Modern money is currency plus demand deposits, and both are linked to the banking system.
- Banks stand between depositors and borrowers and earn the difference between the interest they charge on loans and the interest they pay on deposits.
- Credit can increase earnings or create a debt trap, depending on the risk in the situation and the support available in case of loss.
- Credit comes from formal and informal sources with very different terms.
- Richer households get most credit from formal sources while poor households depend on costly informal credit.
- Formal credit must expand and reach the poor; self-help groups and the Grameen Bank show how organisation can make this possible.
Related chapters: where Money and Credit sits in Class 10 Economics
Money and Credit sits between two chapters in the Class 10 Economics book, and both connections matter.
The previous chapter, Sectors of the Indian Economy, shows how the economy is organised into primary, secondary and tertiary sectors; this chapter explains the money and credit that keep those sectors running.
The next chapter, Globalisation and the Indian Economy, widens the picture to trade and investment across borders.
For everything around this book, start at the Class 10 Social Science hub.
Sources and data verification
This listing is maintained for the 2026-27 academic session using the NCERT textbook information available to us. NCERT remains the authority for confirming the latest edition.
This page describes Chapter 3 of the NCERT Class 10 Social Science textbook Understanding Economic Development, official edition on ncert.nic.in, maintained for the current academic session.
The page numbers, section structure, figures and exercises above describe that NCERT edition. NCERT settles the textbook, its editions and its official PDFs; CBSE settles the curriculum and examinations. Because textbook contents and the examinable syllabus are not always identical, treat the official syllabus as the authority for what is examinable.
No external review process is claimed; every fact on this page traces to the NCERT chapter cited beside it.
Money and Credit Class 10: quick answers
Quick answers to the questions students search for most often about this chapter.
What is double coincidence of wants in Money and Credit class 10?
It is the barter condition where what one person wants to sell is exactly what another wants to buy. In the chapter’s example, the shoe manufacturer must find a wheat farmer who also wants shoes. Money removes this condition by acting as the intermediate step in every exchange (NCERT, p. 39).
Why are demand deposits considered money?
Because they can be withdrawn on demand and, through cheques, used to settle payments directly without cash. Since demand deposits are accepted widely as a means of payment, they count as money along with currency (NCERT, pp. 40-41).
What is the difference between formal and informal sources of credit?
Formal sources — banks and cooperatives — are supervised by the Reserve Bank of India and charge lower interest. Informal sources — moneylenders, traders, employers, relatives and friends — have no supervisor and charge much higher interest, so their loans cost the borrower far more (NCERT, p. 48).
Why do banks ask for collateral before giving a loan?
Collateral is a borrower’s asset that the lender can sell if the loan is not repaid. Banks ask for it to protect the money they lend, which is the public’s deposits. This is also why poor borrowers, who own little, find it harder to get bank loans (NCERT, p. 44).
How do Self Help Groups help the poor get loans?
An SHG of 15-20 members saves regularly for a year or two and then becomes eligible for a bank loan in the group’s name. The group decides each member’s loan and is collectively responsible for repayment, so the bank does not need individual collateral. Members also borrow from the group itself at interest lower than a moneylender’s (NCERT, pp. 50-51).
How can I download the official Money and Credit Class 10 chapter PDF?
Use the official Money and Credit Class 10 chapter PDF link on this page — it goes to the NCERT website, where the official edition is published free. The file matches the printed textbook, pages 37 to 52, and works for offline reading.
| What the chapter holds | Count | Where it is used |
|---|---|---|
| Printed pages | 16 | |
| Figures with NCERT captions | 11 | |
| Tables | 3 | |
| Exercise questions | 35 | answered in our NCERT Solutions |
| Official NCERT PDF | Download the chapter PDF | the chapter exactly as NCERT publishes it |
Reference: NCERT Class 10 Social Science textbook, Chapter 3, official edition on ncert.nic.in.
Explore Class 10 Social Science Books
Related chapters: